One database for market capture and analytical access
Quasar keeps incoming and retained market data available through the same database, with lossless numerical compression to reduce the physical storage footprint.
Its native ORDERBOOK function replays market orders to reconstruct book state at requested times. It can return top-of-book, collapsed Level II, or full Level III output when the required input data is available. The input query supplies events in market order, using source sequence numbers where available, and selects the appropriate exchange engine.
The database layer provides:
Live and historical market data in one database
Native order-book reconstruction from ordered events
Lossless numerical compression for retained history
Analytical queries while ingestion continues
Use native Quasar queries and APIs, or the DuckDB SQL path, to serve downstream applications. Feed integration and application logic define how source events, corrections, and trading workflows are handled.Read the order-book reconstruction documentation →
Watch market-event replay
Follow a 30,000-share buy order as changing liquidity, cancellations, replacements, and fills reshape the order book. See how events stored in Quasar support reconstruction and tracing of the execution.
Generated Nasdaq ITCH-format events, stored in Quasar and replayed for the demonstration.
Watch the demo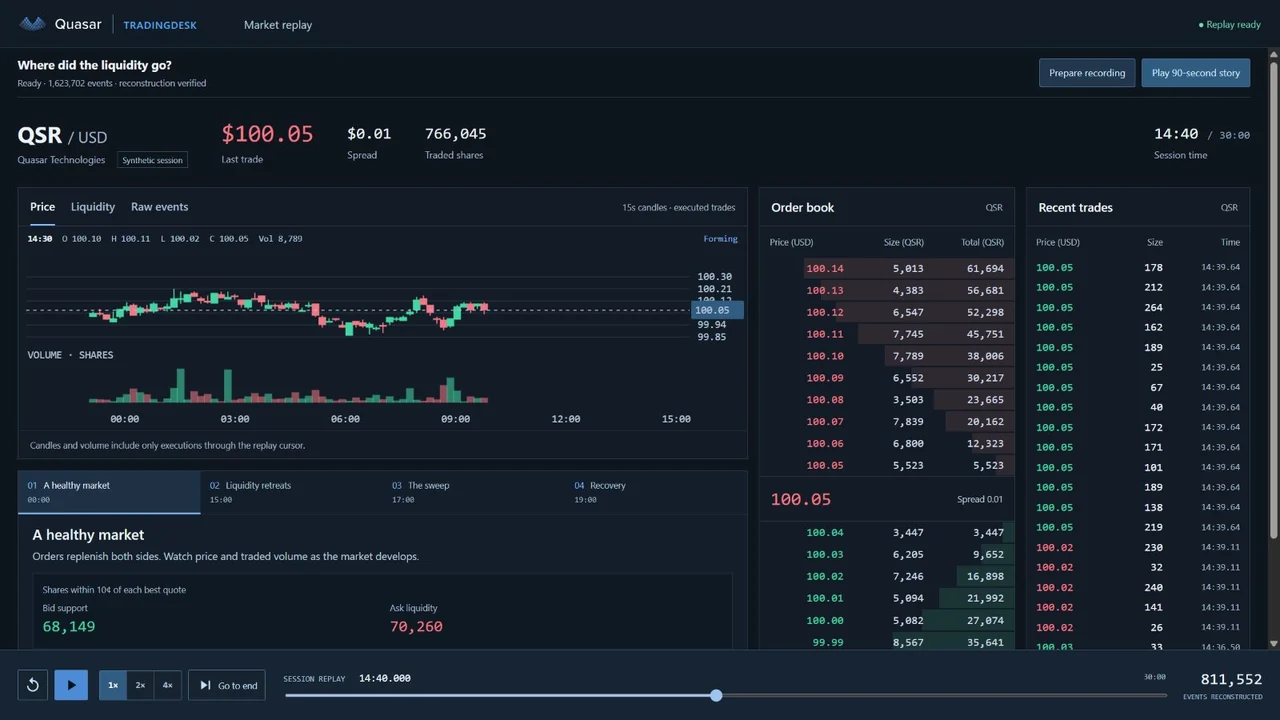
Market-data capabilities and a customer example
Detailed market-event capture
Retain the order, trade, cancellation, and correction events supplied by your feeds, with a schema and ingestion process designed for the source data.
Point-in-time order-book reconstruction
Reconstruct book state using the native ORDERBOOK function, with the required source fields, event ordering, and exchange engine.
Historical data available for analysis
Query retained events for research, replay, and analysis. Compression reduces the physical footprint; retention depth and query performance depend on the deployment and workload.
Customer example: faster price forward curves
An energy-trading customer case study reports 100× faster price forward curve computation using market and weather data. The result describes that customer’s PFC workflow.